B2B lead generation
Sales
Agency Operations
How Much Do Marketing Agency Owners Make? Salary and Total Pay
· Updated
How much do marketing agency owners make? One historical benchmark is about $267k in average combined owner compensation in the 2024 Digital Services Salary Guide from Promethean Research and the Bureau of Digital. The report covers 104 owners at 67 US and Canadian digital-service agencies, with self-reported data collected in November and December 2023. That sample is not a current market average or a beginner-income forecast.
We recommend reading agency-owner salary separately from total compensation, business revenue and business profit. Before comparing an earnings figure with your own situation, check the reporting period, the costs included and whether it describes the business or an individual owner.
Review the benchmark as historical compensation data
The report’s owner-compensation table lists average salary of $132,944, dividends or withdrawals of $123,645, other cash compensation of $4,511 and bonuses of $5,599. Its combined compensation headline therefore includes more than salary. These are historical survey figures, not a recommended pay package.
We suggest using this sample as context rather than treating it as the amount a new marketing-agency owner should expect. Check whether the businesses surveyed resemble yours, and keep this digital-services sample separate from employee salary listings or a selected client success story.
Check what the headline actually measures
A useful first question is whether a figure describes billed work, recognized revenue under the business’s reporting method, cash received, a recurring run rate or a particular result period. Ask the operator or their records rather than assuming the same meaning each time the word “earnings” appears.
Review business profit and owner compensation separately as well. Check which expenses were deducted and how the owner’s own work and payments are represented in that report. Do not label money as personal take-home pay because it remains after a partial list of costs.
Consider a worked example with visible assumptions
For this illustrative monthly model, choose revenue and business costs as separate inputs. The cost input here covers delivery labor, tools, acquisition and other operating expenses, but excludes owner compensation, taxes and cash reserves. It is a deliberately limited planning model, not an accounting policy or an observed agency’s results.
Client Ascension calculation: illustrative monthly example, 30000 dollars of revenue minus 20000 dollars of business costs leaves 10000 dollars before owner compensation, taxes and reserves. These inputs are invented and do not describe a client result.
Check what the remainder does and does not answer. In this example it does not establish how much an owner should withdraw, how their payment is classified or what the business needs to retain. Review those decisions with the business’s actual records and appropriate professional support rather than treating the model as spendable personal income.
Review the costs that a service package must support
Choose a cost review that includes delivery, quality checking, client communication, tools and acquisition work. Founder labor should remain visible even when the founder performs it personally. Consider what it would take to keep serving the client if another competent person had to do that work.
The service-pricing guide can help examine price, demand and fulfillment assumptions. A higher fee is not by itself evidence of higher owner pay; review the workload and costs associated with it. Likewise, a larger team or a broader package should not be treated as proof that the owner’s position improved.
Check timing, customer concentration and cash separately
We suggest comparing the same reporting periods and recording when work is agreed, delivered, billed and paid. An isolated strong month, a recurring run rate and cash collected over a longer period should not be silently substituted for one another.
Review how much depends on a particular customer, whether work must continue after payment and which obligations still need funding. These questions can help explain why an attractive revenue number is not enough to decide what an owner can safely commit to paying themselves. This guide does not prescribe a withdrawal amount or tax treatment.
Review retained case images as historical claims, not salary data
We recommend treating the retained case-study images as historical promotional claims, not as owner-pay records or an industry salary survey. Check the underlying account for the business, metric, period and limitations before making a comparison; an image of revenue cannot establish a reader’s future personal income.
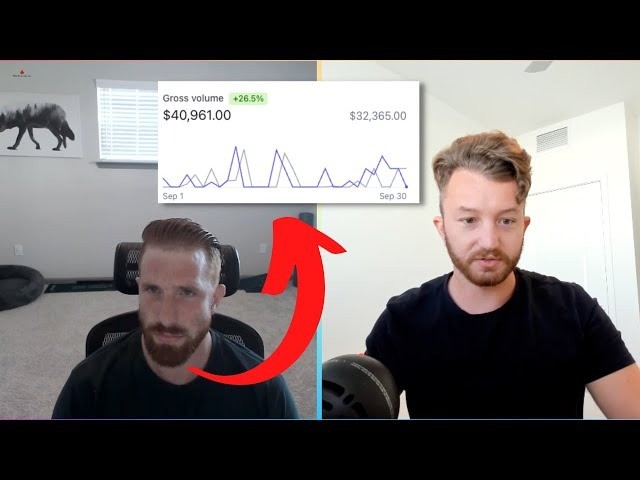
As separate related reading, consider Kyle’s recruitment-agency account for the importance of distinguishing recurring revenue, placement fees and future targets. We recommend reading the stated metric rather than converting a case headline into an owner’s personal income. Selected operator accounts cannot establish a typical result for the market.
Choose a practical earnings review for your own business
We suggest assembling a dated view of revenue, costs, owner payments and cash obligations with consistent definitions. Note which numbers are known, which are estimates and which belong to another period. Review an unexplained increase or decline before deciding which service, price or hiring change to make.
Use the productized-service guide when examining the relationship between scope, recurring work and delivery capacity. The useful question is whether the agreement can support the work and responsibilities involved, not whether another agency’s headline revenue makes the model sound attractive.
If you are considering outside support, review the AI Assisted Agency program page as separate related reading. We recommend checking whether an option addresses the implementation work you need help with.
Prepared by Client Ascension with AI assistance. Documentation checked 2026-11-10.